What is an offset mortgage, and who does it suit?
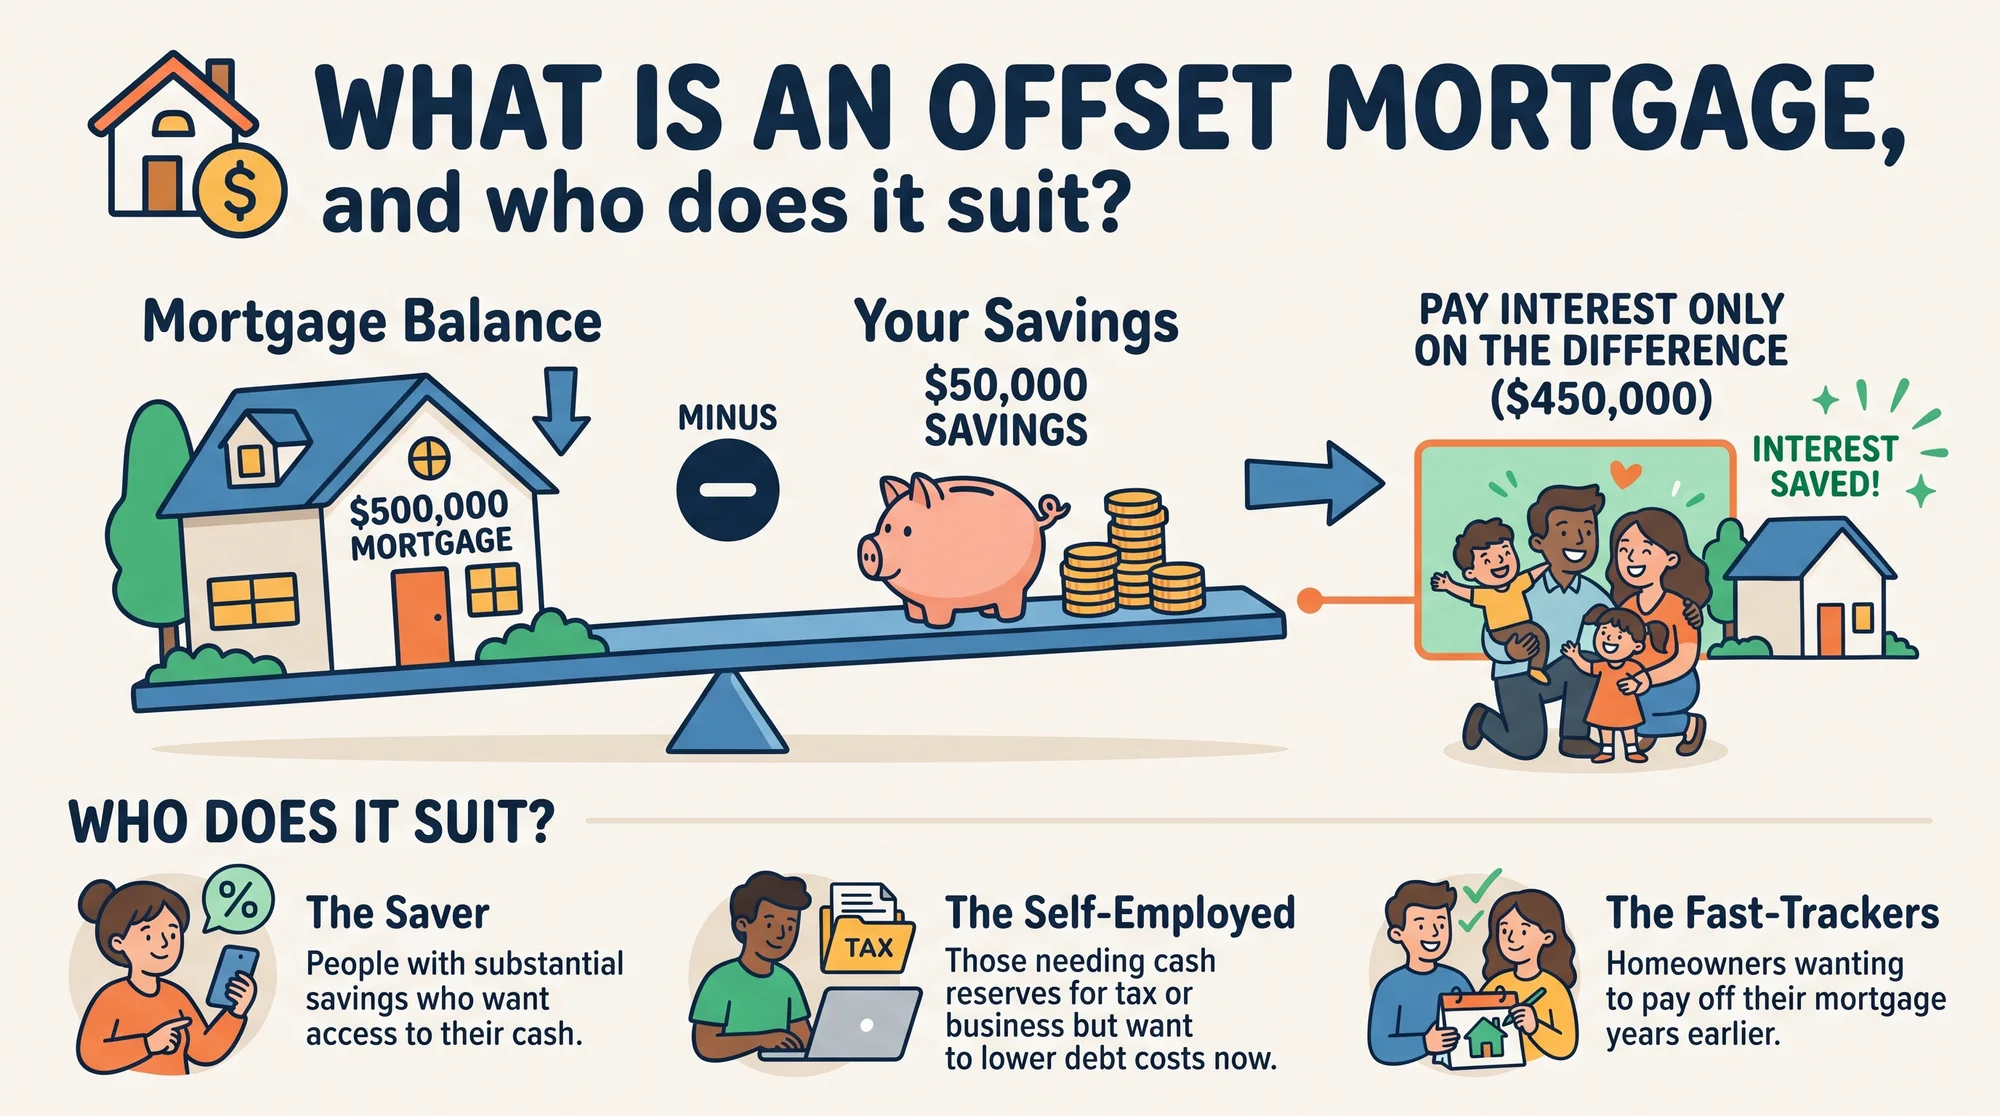
An offset mortgage links one or more everyday or savings accounts to your home loan. You are charged interest on the loan balance less the money in those accounts. Your savings earn nothing, but they save you interest at the mortgage rate, every day, and you can still spend them.
How the interest works
Suppose you owe $500,000 and keep $20,000 across your linked accounts. Interest is charged on $480,000. If your pay goes in and your bills go out, the balance in the accounts rises and falls through the month, and the interest follows it day by day. Repayments stay the same, so the saved interest goes to principal and the loan ends sooner.
There is no tax on the saving. Interest earned on a savings account is income and taxed at your rate; interest you do not pay is not. That is why offsetting beats a savings account paying the same rate, before you even allow for the mortgage rate being higher.
What it costs
Offset loans are floating-rate loans, and floating rates are usually higher than the fixed rates on offer. Some lenders also charge a monthly fee. So an offset only wins when the savings held against it are large enough for the interest saved to beat the extra rate on the whole loan. With a small balance and a large loan, a fixed rate on the lot costs less.
The common answer is to split: fix most of the loan and put an offset portion about the size of the savings you keep plus the money passing through each month. The offset part then does its work without paying the floating rate on the rest.
A worked example
A $500,000 loan over 30 years, fixed at 5.99%, against an offset loan at 6.49% with $20,000 of savings and $500 added to them each month: the offset loan clears in 273 months, 87 months sooner than the fixed loan, and saves $218,686 of interest. The higher rate is overtaken because the savings keep growing and the interest saved compounds.
Put your own loan, rates and savings in below.
Live comparison
Fixed vs offset mortgage
See how an offset savings account can beat a lower fixed rate and pay the loan off early.
Whole-of-term comparison
The offset option could save you in interest
and clear the loan 15 months early - repaid in 8 years 9 months instead of 10 years.
Effective interest rate
Fixed mortgage
5.07%
4.99% advertised
Offset mortgage
3.52%
6.14% advertised
Interest on the offset loan is only charged on the balance minus your savings, so the 6.14% loan effectively costs just 3.52% a year.
Fixed mortgage
4.99% p.a.
- Monthly
- $7,421
- Total interest
- $190,540
- Total paid
- $890,540
- Paid off in
- 10 years
Offset mortgage
6.14% p.a.
- Monthly
- $7,821
- Total interest
- $114,299
- Total paid
- $814,299
- Paid off in
- 8 years 9 months
The offset mortgage carries a higher rate but links a savings account ($170,000 opening + $500/month) that reduces the interest-bearing balance, so more of each payment clears principal. Estimate only.
Loan balance over time
The offset mortgage reaches zero earlier despite the higher rate.
Fixed vs offset balance
Both start at the loan amount; the offset loan is paid off first.
Interest paid over time
How much interest each option costs across the first years and the whole term.
| Period | Fixed4.99% p.a. | Offset6.14% p.a. | You saveOffset vs fixed |
|---|---|---|---|
| 1 year | $33,675 | $31,535 | $2,140 |
| 2 years | $64,050 | $56,240 | $7,810 |
| 3 years | $91,671 | $77,496 | $14,175 |
| Whole term | $190,540 | $114,299 | $76,240 |
Offset schedule
Each month of the offset loan: your payment, where it goes, and your savings against what you owe.
| Month | Payment | Interest | Principal | Offset balance | Loan balance |
|---|---|---|---|---|---|
| 1 | $7,821 | $3,582 | $4,239 | $170,500 | $695,761 |
| 2 | $7,821 | $2,688 | $5,133 | $171,000 | $690,628 |
| 3 | $7,821 | $2,659 | $5,162 | $171,500 | $685,466 |
| 4 | $7,821 | $2,630 | $5,191 | $172,000 | $680,275 |
| 5 | $7,821 | $2,601 | $5,220 | $172,500 | $675,055 |
| 6 | $7,821 | $2,571 | $5,249 | $173,000 | $669,805 |
| 7 | $7,821 | $2,542 | $5,279 | $173,500 | $664,527 |
| 8 | $7,821 | $2,512 | $5,308 | $174,000 | $659,218 |
| 9 | $7,821 | $2,483 | $5,338 | $174,500 | $653,880 |
| 10 | $7,821 | $2,453 | $5,368 | $175,000 | $648,512 |
| 11 | $7,821 | $2,423 | $5,398 | $175,500 | $643,114 |
| 12 | $7,821 | $2,393 | $5,428 | $176,000 | $637,686 |
| 13 | $7,821 | $2,362 | $5,458 | $176,500 | $632,228 |
| 14 | $7,821 | $2,332 | $5,489 | $177,000 | $626,739 |
| 15 | $7,821 | $2,301 | $5,520 | $177,500 | $621,219 |
| 16 | $7,821 | $2,270 | $5,550 | $178,000 | $615,669 |
| 17 | $7,821 | $2,239 | $5,581 | $178,500 | $610,088 |
| 18 | $7,821 | $2,208 | $5,612 | $179,000 | $604,475 |
| 19 | $7,821 | $2,177 | $5,644 | $179,500 | $598,832 |
| 20 | $7,821 | $2,146 | $5,675 | $180,000 | $593,156 |
| 21 | $7,821 | $2,114 | $5,707 | $180,500 | $587,450 |
| 22 | $7,821 | $2,082 | $5,739 | $181,000 | $581,711 |
| 23 | $7,821 | $2,050 | $5,770 | $181,500 | $575,941 |
| 24 | $7,821 | $2,018 | $5,803 | $182,000 | $570,138 |
| 25 | $7,821 | $1,986 | $5,835 | $182,500 | $564,303 |
| 26 | $7,821 | $1,954 | $5,867 | $183,000 | $558,436 |
| 27 | $7,821 | $1,921 | $5,900 | $183,500 | $552,536 |
| 28 | $7,821 | $1,888 | $5,933 | $184,000 | $546,604 |
| 29 | $7,821 | $1,855 | $5,965 | $184,500 | $540,639 |
| 30 | $7,821 | $1,822 | $5,999 | $185,000 | $534,640 |
| 31 | $7,821 | $1,789 | $6,032 | $185,500 | $528,608 |
| 32 | $7,821 | $1,756 | $6,065 | $186,000 | $522,543 |
| 33 | $7,821 | $1,722 | $6,099 | $186,500 | $516,444 |
| 34 | $7,821 | $1,688 | $6,133 | $187,000 | $510,312 |
| 35 | $7,821 | $1,654 | $6,166 | $187,500 | $504,145 |
| 36 | $7,821 | $1,620 | $6,201 | $188,000 | $497,945 |
| 37 | $7,821 | $1,586 | $6,235 | $188,500 | $491,710 |
| 38 | $7,821 | $1,551 | $6,269 | $189,000 | $485,441 |
| 39 | $7,821 | $1,517 | $6,304 | $189,500 | $479,137 |
| 40 | $7,821 | $1,482 | $6,339 | $190,000 | $472,798 |
| 41 | $7,821 | $1,447 | $6,374 | $190,500 | $466,424 |
| 42 | $7,821 | $1,412 | $6,409 | $191,000 | $460,015 |
| 43 | $7,821 | $1,376 | $6,444 | $191,500 | $453,571 |
| 44 | $7,821 | $1,341 | $6,480 | $192,000 | $447,091 |
| 45 | $7,821 | $1,305 | $6,516 | $192,500 | $440,576 |
| 46 | $7,821 | $1,269 | $6,551 | $193,000 | $434,024 |
| 47 | $7,821 | $1,233 | $6,588 | $193,500 | $427,437 |
| 48 | $7,821 | $1,197 | $6,624 | $194,000 | $420,813 |
| 49 | $7,821 | $1,161 | $6,660 | $194,500 | $414,153 |
| 50 | $7,821 | $1,124 | $6,697 | $195,000 | $407,456 |
| 51 | $7,821 | $1,087 | $6,734 | $195,500 | $400,722 |
| 52 | $7,821 | $1,050 | $6,771 | $196,000 | $393,952 |
| 53 | $7,821 | $1,013 | $6,808 | $196,500 | $387,144 |
| 54 | $7,821 | $975 | $6,845 | $197,000 | $380,298 |
| 55 | $7,821 | $938 | $6,883 | $197,500 | $373,415 |
| 56 | $7,821 | $900 | $6,921 | $198,000 | $366,495 |
| 57 | $7,821 | $862 | $6,959 | $198,500 | $359,536 |
| 58 | $7,821 | $824 | $6,997 | $199,000 | $352,539 |
| 59 | $7,821 | $786 | $7,035 | $199,500 | $345,504 |
| 60 | $7,821 | $747 | $7,074 | $200,000 | $338,431 |
| 61 | $7,821 | $708 | $7,112 | $200,500 | $331,318 |
| 62 | $7,821 | $669 | $7,151 | $201,000 | $324,167 |
| 63 | $7,821 | $630 | $7,191 | $201,500 | $316,976 |
| 64 | $7,821 | $591 | $7,230 | $202,000 | $309,746 |
| 65 | $7,821 | $551 | $7,269 | $202,500 | $302,477 |
| 66 | $7,821 | $512 | $7,309 | $203,000 | $295,168 |
| 67 | $7,821 | $472 | $7,349 | $203,500 | $287,819 |
| 68 | $7,821 | $431 | $7,389 | $204,000 | $280,429 |
| 69 | $7,821 | $391 | $7,430 | $204,500 | $273,000 |
| 70 | $7,821 | $350 | $7,470 | $205,000 | $265,529 |
| 71 | $7,821 | $310 | $7,511 | $205,500 | $258,018 |
| 72 | $7,821 | $269 | $7,552 | $206,000 | $250,466 |
| 73 | $7,821 | $228 | $7,593 | $206,500 | $242,873 |
| 74 | $7,821 | $186 | $7,635 | $207,000 | $235,239 |
| 75 | $7,821 | $144 | $7,676 | $207,500 | $227,562 |
| 76 | $7,821 | $103 | $7,718 | $208,000 | $219,844 |
| 77 | $7,821 | $61 | $7,760 | $208,500 | $212,084 |
| 78 | $7,821 | $18 | $7,802 | $208,500 | $204,282 |
| 79 | $7,821 | $0 | $7,821 | $208,500 | $196,461 |
| 80 | $7,821 | $0 | $7,821 | $208,500 | $188,640 |
| 81 | $7,821 | $0 | $7,821 | $208,500 | $180,819 |
| 82 | $7,821 | $0 | $7,821 | $208,500 | $172,999 |
| 83 | $7,821 | $0 | $7,821 | $208,500 | $165,178 |
| 84 | $7,821 | $0 | $7,821 | $208,500 | $157,357 |
| 85 | $7,821 | $0 | $7,821 | $208,500 | $149,536 |
| 86 | $7,821 | $0 | $7,821 | $208,500 | $141,716 |
| 87 | $7,821 | $0 | $7,821 | $208,500 | $133,895 |
| 88 | $7,821 | $0 | $7,821 | $208,500 | $126,074 |
| 89 | $7,821 | $0 | $7,821 | $208,500 | $118,253 |
| 90 | $7,821 | $0 | $7,821 | $208,500 | $110,433 |
| 91 | $7,821 | $0 | $7,821 | $208,500 | $102,612 |
| 92 | $7,821 | $0 | $7,821 | $208,500 | $94,791 |
| 93 | $7,821 | $0 | $7,821 | $208,500 | $86,971 |
| 94 | $7,821 | $0 | $7,821 | $208,500 | $79,150 |
| 95 | $7,821 | $0 | $7,821 | $208,500 | $71,329 |
| 96 | $7,821 | $0 | $7,821 | $208,500 | $63,508 |
| 97 | $7,821 | $0 | $7,821 | $208,500 | $55,688 |
| 98 | $7,821 | $0 | $7,821 | $208,500 | $47,867 |
| 99 | $7,821 | $0 | $7,821 | $208,500 | $40,046 |
| 100 | $7,821 | $0 | $7,821 | $208,500 | $32,225 |
| 101 | $7,821 | $0 | $7,821 | $208,500 | $24,405 |
| 102 | $7,821 | $0 | $7,821 | $208,500 | $16,584 |
| 103 | $7,821 | $0 | $7,821 | $208,500 | $8,763 |
| 104 | $7,821 | $0 | $7,821 | $208,500 | $942 |
| 105 | $942 | $0 | $942 | $208,500 | Paid off |
Loan balance over time
The offset mortgage reaches zero earlier despite the higher rate.
Fixed vs offset balance
Both start at the loan amount; the offset loan is paid off first.
Who gets the most from an offset
People who keep real savings, an emergency fund or money set aside for tax, and want it to work without locking it away.
Self-employed people and others with lumpy income who hold cash between payments.
Families whose relatives will link their savings to the loan; some lenders allow accounts in other names.
Anyone paid monthly with bills spread through the month: the float between them reduces interest every day.
Who it suits less
Borrowers with little cash on hand. The floating rate on the offset portion is a real cost, and with nothing to offset it is a cost for nothing.
Anyone who would spend the savings because they are visible and easy to reach. An offset rewards leaving the money alone.
Borrowers who want the certainty of one fixed repayment for the whole loan. An offset portion floats.
Offset or revolving credit?
A revolving credit loan does a similar job by letting you pay money into the loan itself and redraw it. The maths is the same; the difference is where the money sits. An offset keeps your savings in ordinary accounts, which many people find easier to manage and to keep separate. A revolving credit facility has one balance and needs discipline about the limit.
For an adviser working out how much of a client's loan to leave floating against an offset, and at which lender, the Best Structure Finder prices the whole structure at each lender's rates. If you are weighing an offset as part of a move to another lender, Should I refinance? covers the cashback and break-fee side.