Skip to content
EnhancedMortgage

Best Deal CheckMortgage refinance calculator

Enter your mortgage as it is today and the rate you could switch to, and this calculator shows three paths: staying put, switching to the new rate, and switching with the cashback and your everyday balance working in an offset account. It reports the interest saved and how much sooner the loan is paid off on each.

Rate check

Would refinancing save you money?

Your mortgage today against a switch to today's rate for your fixed term, with an offset account working for you.

Your mortgage

Per year
Optional - if they have the lowest rate, it is a refix
Which market rate to compare against

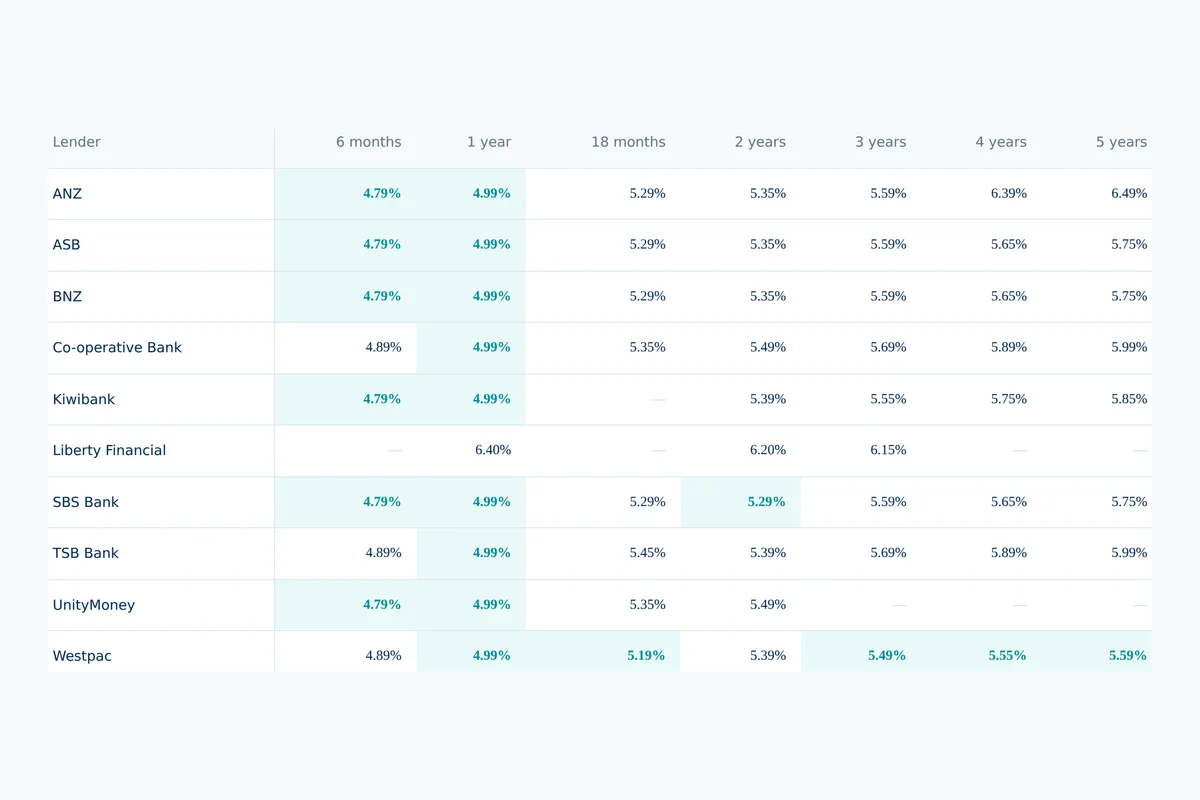
Today's lowest 1 year rate from Rates Hub: 4.99% (ANZ Special), as at 18 Nov 2026.

What you pay today

Leave at $0 to use the minimum your loan requires

Working harder for you

Into the offset account each month
Average balance of your everyday account(s)
Optional - shows your LVR

Description

Compares your mortgage as it stands with a refinance to today's rate for your fixed term, and with an optimal solution that keeps your current repayment and puts the difference, your extra, the cashback and your everyday balance into an offset account.

Assumptions

  • We assume each fixed period is re-fixed at the same rate rather than dropping to floating. Actual future rates will differ.
  • Savings are measured against your loan contract: your current rate, the required repayment and the remaining term. If you already pay more than you must, part of the saving comes from those extra repayments, and we say how much.
  • Cashback assumes 1% of your balance less $1,500 legal costs, and only when you move lender: a refix with your own lender has neither. Lender offers vary, are often capped, and carry conditions.
  • A repayment below what your loan requires is replaced by the required minimum. Fortnightly repayments are converted to a monthly equivalent (x 26 / 12).
  • The offset account reduces the balance interest is charged on, not the balance you owe. Once it covers the loan, that month is treated as the finish line.
  • The market rate shown may not be available above 80% LVR, where lenders add a margin.

Your optimal solution

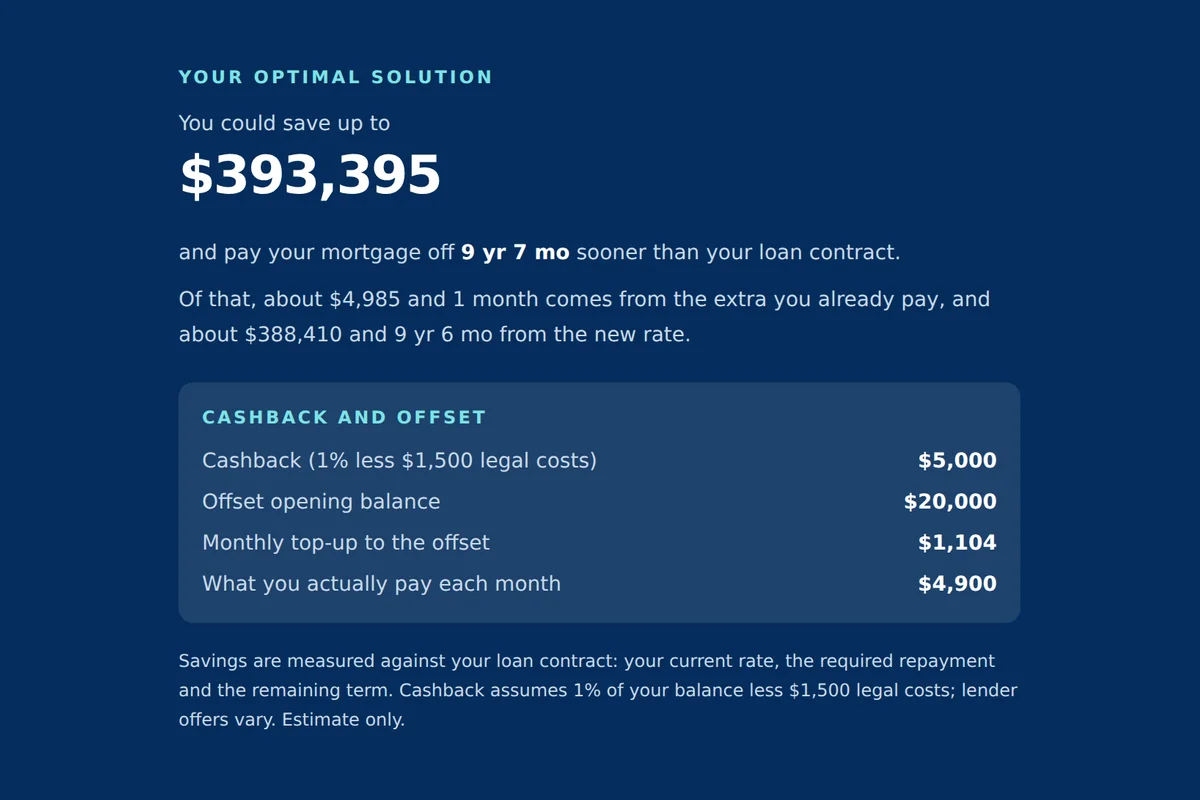
You could save up to

$393,395

and pay your mortgage off 9 yr 7 mo sooner than your loan contract.

Of that, about $4,985 and 1 month comes from the extra you already pay, and about $388,410 and 9 yr 6 mo from the new rate.

Cashback and offset

Cashback (1% less $1,500 legal costs)
$5,000
Offset opening balance
$20,000
Monthly top-up to the offset
$1,104
What you actually pay each month
$4,900

Savings are measured against your loan contract: your current rate, the required repayment and the remaining term. Cashback assumes 1% of your balance less $1,500 legal costs; lender offers vary. Estimate only.

Comparison table

MeasureYour loan contractCurrent rate 6.5%, required repaymentYour new loanNew rate 4.99%, required repaymentYour optimal solutionRecommendedNew rate 4.99% + keep your current repayment + pay extra
Minimum monthly repayment$4,389$3,796$3,796
Your actual repayment——$4,400
Payoff time25 years25 years15 yr 5 mo
Total interest amount$666,654$488,815$273,259
Interest saved (from your loan contract)—$177,839$393,395
Time saved——9 yr 7 mo

Interest saved over time

"Your loan contract" vs "Your optimal solution" - cumulative interest saved at each point.

1 year

$11,132

2 years

$22,974

3 years

$35,552

Whole term

$393,395

Loan balance over time

Your optimal solution shows what you owe less your offset account, so it reaches $0 the month the offset covers the loan.

Your loan contract vs your new loan vs your optimal solution

Each loan ends when it is paid off.

Your loan contractYour new loanYour optimal solution
$0$200K$400K$600K$800K202620312036204120462051

Best Deal Check: how it works

What this calculator shows you

Best Deal Check showing $393,395
  • Potential interest saving against your loan contract, and how much sooner the loan is paid off
  • Cashback, offset opening balance and monthly top-up
  • What you actually pay each month
  • Chart: your loan contract, a new loan, and your optimal solution

How to use it

  1. Enter your balance, current rate and remaining term.
  2. Choose your current lender, or leave it blank.
  3. Choose how long is left on your fixed term.
  4. Check the new rate: it opens on today's rate for that term, and you can overtype it with a rate you have been offered.
  5. Add your current repayment, any extra you can pay and your everyday account balance.
  6. Read the saving and compare the three lines on the chart.

Why use it

For your clients

  • Shows whether switching is worth the effort before talking to a bank.

For your business

  • Starts refinance conversations with real numbers.

How it works

  • Cashback is 1% of the loan less $1,500 of legal costs, never below zero, and only when you move lender; it opens the offset account along with your everyday balance.
  • The new rate applies for the whole remaining term. Break fees are not included.
  • Savings are measured against your loan contract: your current rate, the required repayment and the remaining term. A repayment below the required one is raised to it.
  • The opening rate is the lowest Special or Standard rate a lender publishes for the term, as on My Rate Check. If your own lender has that rate, or ties for it, it is treated as a refix with them: no cashback and no legal fees.
  • The maths is the MyRateCheck engine's, kept exactly.

Worked example: A $650,000 loan at 6.5% with 300 months to run and 12 months left fixed, switched to 4.99% while paying $4,400 a month plus $500 extra with $15,000 in the everyday account: against the loan contract the new rate alone saves $177,839 of interest, and the optimal solution, with $5,000 of cashback and the offset, saves $393,395 and clears the loan 115 months sooner.

Common questions

What about break fees?
Breaking a fixed rate early can cost a fee. Check with your lender; the calculator does not include it.
Is cashback free money?
Cashback usually comes with conditions and can be clawed back if you leave the lender within a set time.
Why does an offset help?
Money in an offset account reduces the balance you are charged interest on, without locking the money away.

Related calculators

  • EnhancedMortgage

    Today's Best Rates

    What are the banks charging today?

    Each lender's lowest published home-loan rate for every fixed term, refreshed hourly, with the lowest in each term highlighted.

    Shows: Published New Zealand home loan rates by lender and fixed term, with the lowest in each term marked.
  • EnhancedMortgage

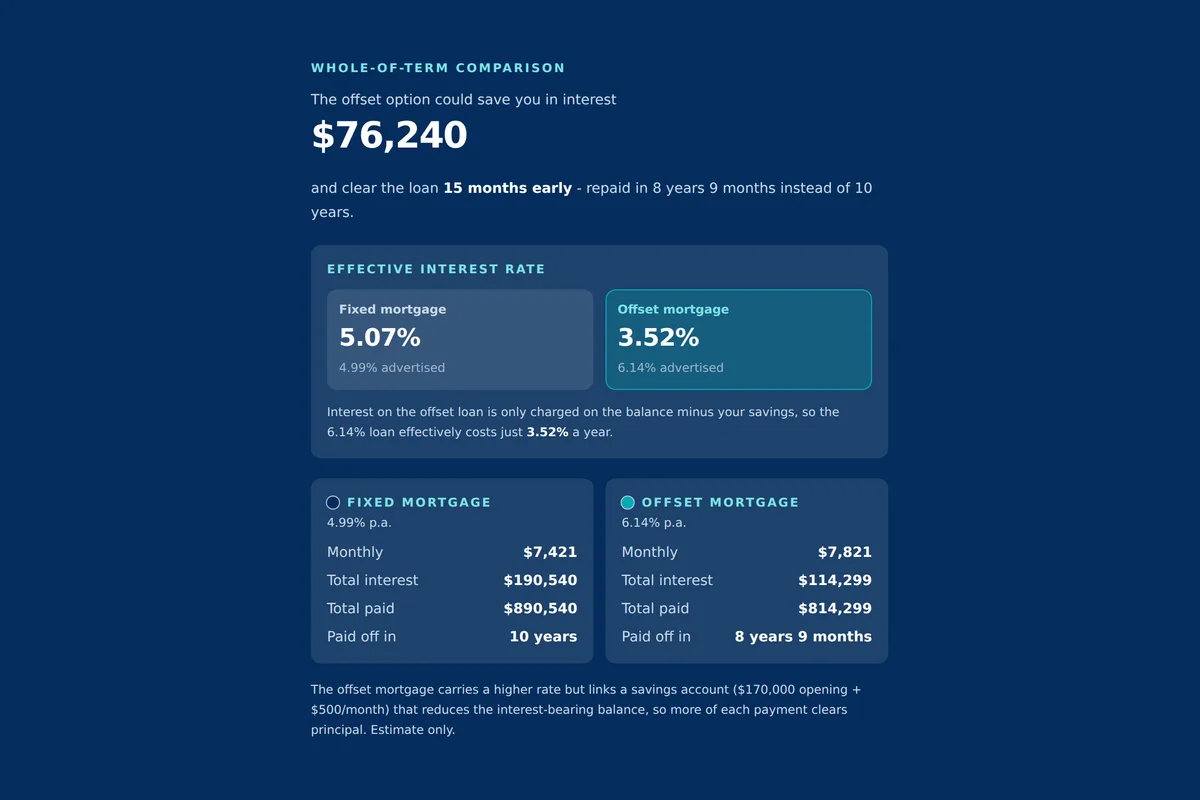
    Offset Saver

    Would an offset account clear my loan sooner?

    Shows how savings held in an offset account cut interest and shorten the loan, compared with a standard fixed loan.

    Shows: A standard loan against an offset loan at its own rate: the payoff date, the interest paid, and the difference over two and three years.

  • BasicAll industries

    Mortgage-Free Date

    When will I be mortgage-free?

    See when your mortgage will be paid off, and how much time and interest extra repayments or a lump sum could save.

    Shows: When your mortgage is paid off at today's repayments, and how much sooner - and how much less interest - with a little extra each payday or a lump sum.

This calculator provides illustrative estimates based on your inputs and the stated assumptions. It is not financial advice. Consider consulting a qualified financial or mortgage adviser about your circumstances.

Last updated 6 October 2026 · Rates as at 18 Nov 2026